Housing that isn't for sale
Nearly eight million European homes are held in cooperative forms, from Zurich to Warsaw. What members actually own, why the model protects affordability, and why it has stopped growing where it is wanted most.
What do you actually own?
Picture yourself signing for a flat in a Zurich cooperative. You pay a deposit that looks like a down payment and a monthly charge that looks like rent. When you move out fifteen years later you get the deposit back, with nothing added for whatever the building did on the property market meanwhile. That is not a deal gone wrong. That is the deal.
A housing cooperative is a member-owned organisation through which people arrange housing for themselves. That is the whole of the shared definition, and what membership buys differs enough across Europe that the same word covers two different bargains.
In rental and right-of-use cooperatives, the organisation keeps the building. Members hold an occupancy right written into the statutes, charges follow what the housing costs rather than what the market will bear, and the value at exit is capped or absent. In ownership-aligned cooperatives the member holds a transferable share attached to a flat, and once that share trades at a market price the protection thins out. The national datasets put roughly 5.3 million European homes in the first group and about half that number in the second. The line is drawn by how each country classifies its stock rather than by how any one building behaves, so several of the national totals further down sit on the other side of it from where you might expect.
The spectrum below sorts tenures by how far a home sits from the market. Drag the marker to see what each form protects, and what it leaves exposed.
The democratic part is written down, not assumed. The International Co-operative Alliance’s seven principles — from open membership and democratic member control to cooperation between cooperatives — are the working constitution most European housing cooperatives copy into their statutes.
Two neighbouring ideas keep getting confused with it. Social housing describes the terms on which a home is let, not who owns the landlord, which is why Austria’s limited-profit cooperatives can be both at once. A condominium splits private ownership of flats from joint management of the roof, and an ownership-aligned cooperative with freely tradable shares behaves much like one. An investor-owned landlord owes its first duty to shareholders; a rental cooperative owes it to the people asleep upstairs.
Under the labels sits an older question: how do people look after something they hold together? Elinor Ostrom found that commons institutions that last share the same design features. Clear boundaries. Rules written by the people the rules bind. Monitoring, and conflict resolution cheap enough to use. And, where the commons sits inside something bigger, nested tiers of governance. Hold on to that last one; it is where this ends up.
Five waves, one stubborn idea
Cooperative housing did not arrive in Europe once. It arrived five times, in different countries and for different reasons, and every wave left behind institutions the next one could borrow. Three things had to line up each time: a legal form that let people organise, finance that did not demand a speculative return, and residents willing to do the work. Where all three held, the stock is still standing a century later.
Click through the waves below. The countries listed under each are the ones that wave shaped most, and you will notice several appear twice.
- 1889[source]
Germany writes cooperatives into law
The Genossenschaftsgesetz gave mutual self-help societies limited liability and a firm legal footing. A movement that had been improvising since the middle of the century could finally borrow like an institution.
- 1920s[source]
Red Vienna pays for housing with a tax
Vienna funded construction through a dedicated housing tax and bought land at scale. Municipal and cooperative provision stayed separate, but public land and public finance became shared plumbing for both.
- 1945–1989[source]
State finance, on both sides of the curtain
Nordic governments lent for construction; centrally planned systems used cooperatives as one delivery channel among several. Poland and Czechia still hold the stock that period produced, though its ownership rules changed later.
- 1980s–1990s[source]
Switzerland rediscovers its members
A new generation of Swiss cooperatives formed around active member involvement rather than professional administration alone. Cities began awarding land by concept rather than by price.
- since 2000[source]
The fifth wave
Resident-led projects answer the affordability crisis with a structure instead of a subsidy: collective ownership, hard limits on private gains, shared space and ecological ambition written into the brief.
Each wave answered a different housing emergency with a different source of money.
Notice how little of this was planned. Each wave began where an existing housing system had already failed a particular group, and each borrowed the legal form left behind by the one before it. Germany’s 1889 statute is still the template for the Genossenschaft building in Berlin today. Vienna’s interwar habit of buying land long before it needed it is the habit Zurich practises now. The fifth wave inherited both, and added a wariness of the professionalised housing organisations the post-war wave produced.
What travels between the waves is the ownership rule. What does not travel is the money. The first wave ran on mutual savings and a new liability statute; the post-war wave ran on state construction loans; the wave happening now runs mostly on whatever a city is prepared to do with its land.
That fifth wave is why you are reading this. It has spread past the old strongholds into the Netherlands and Portugal, and in both places it reconnected with a cooperative tradition that had gone quiet decades earlier. It also carries an argument the earlier waves did not: that the form itself is a reply to housing financialisation, and that a home held for use is the point rather than a means to a cheaper one.
The same word, eight different deals
Cross a border and the word survives while the bargain changes. A Swiss Wohnbaugenossenschaft, a Swedish bostadsrättsförening, a Polish spółdzielnia mieszkaniowa and a Catalan cessió d’ús project are all cooperatives. They part company on who holds the equity, who lends the money and what the state will put on the table.
Start with the map. There is no north–south or east–west pattern to find. The cooperative share tracks the finance and land policy of individual countries, and in several cases a decision taken a century ago.
Switzerland runs the model at city scale. Cooperatives hold close to a fifth of every dwelling in Zurich against 4.3% nationally, spread across roughly fifteen hundred organisations. The enabling condition is municipal land let on long leases. Century-old cooperatives such as ABZ now sit beside fifth-wave buildings like Kalkbreite and Zollhaus. Land terms buy the economics; what the cooperatives do with the room that leaves is their own.
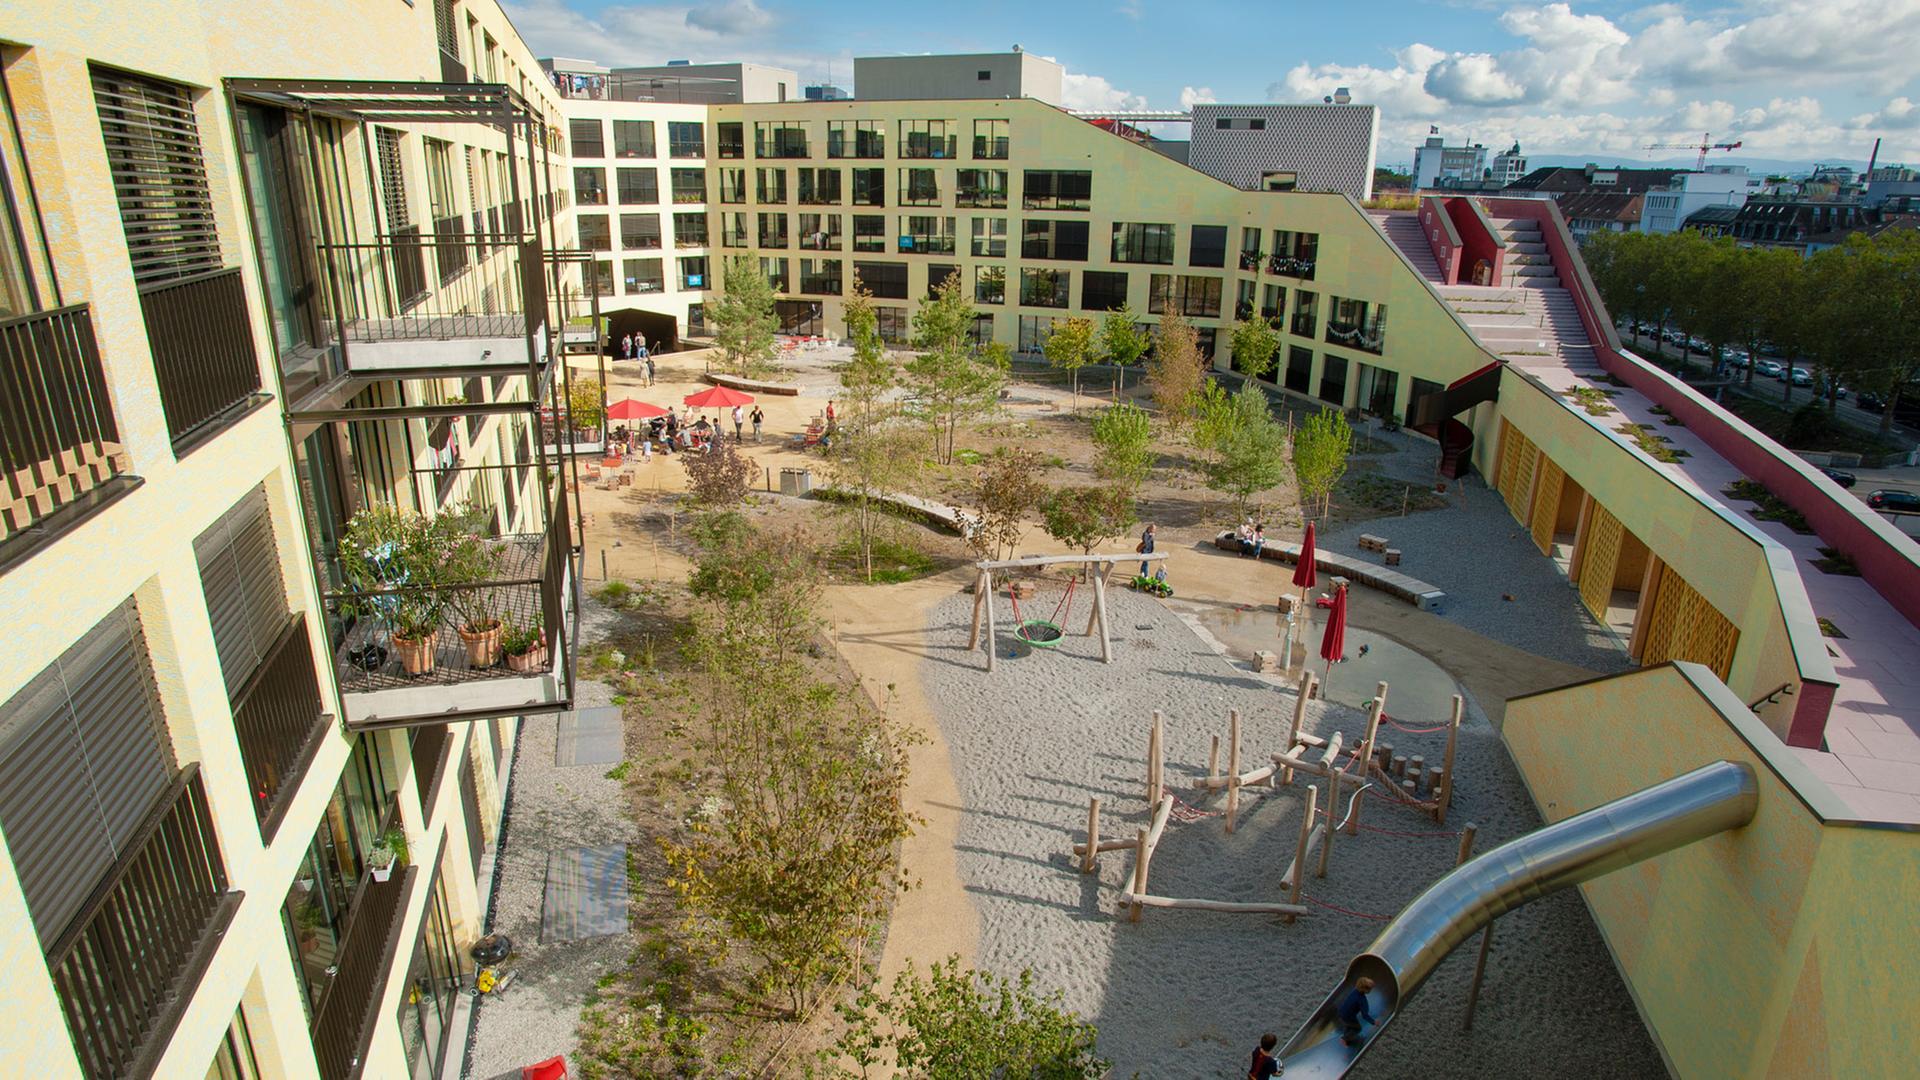
Austria made affordability a matter of statute instead. Its 97 housing cooperatives manage around 460,000 homes inside a limited-profit sector of 998,000, which is more than one Austrian household in ten. The law caps costs, caps returns and dictates what may be done with a surplus. Vienna’s Die HausWirtschaft shows the newer register: flats, workspaces and shared infrastructure run by the members who use them.
Germany holds Europe’s second-largest cooperative stock by unit count, about 2.2 million homes across some 2,237 organisations. Most of it is long-established rental provision that behaves like a landlord rather than a movement. The newer resident-led projects are smaller and noisier: Möckernkiez in Berlin, and Prinz Eugen Park in Munich, on plots the city awarded by concept rather than to the highest bid.
The Nordic sectors are the largest and the least protected. Sweden’s bostadsrätt stock runs to roughly 1.03 million homes across about 28,000 associations; Norway’s runs through federations such as OBOS. Both are ownership-aligned, so shares trade, and where they trade at market prices the affordability advantage erodes within a generation.
Spain is the mirror image: a tiny stock with outsized influence. Around 6,000 dwellings sit in standing cooperative tenure, roughly 0.02% of Spanish housing, once you set aside the build-to-sell cooperatives that dissolve into private ownership on handover. Catalonia’s cessió d’ús model, promoted by Sostre Cívic and proved by La Borda, pairs collective ownership with use rights that cannot be sold.
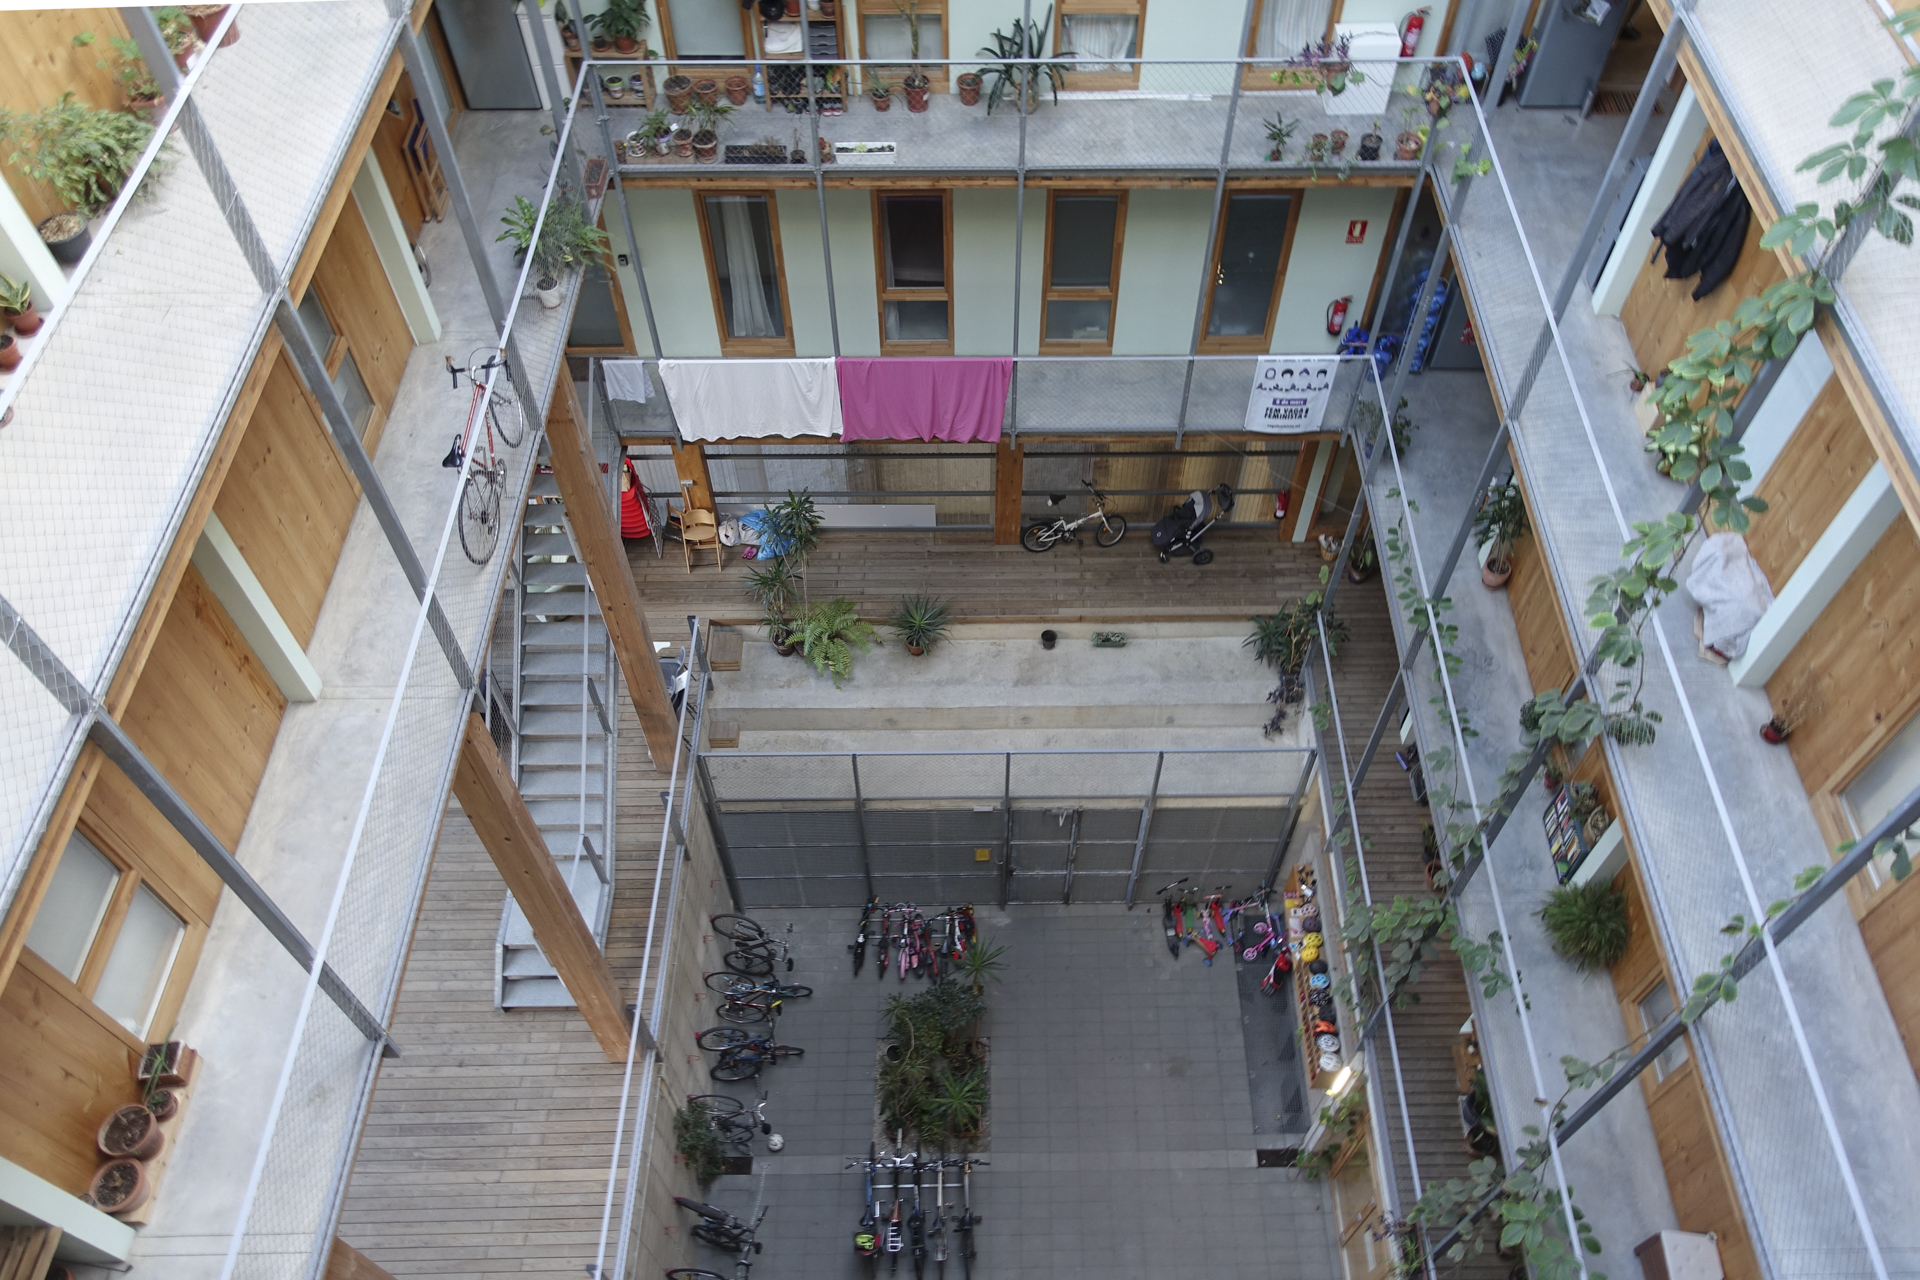
The Netherlands has a vast social-housing sector and almost no cooperatives, around 1,500 dwellings in total. The money is finally moving. Amsterdam lends up to €50,000 per home from a fund announced at €50 million and appropriated at €23.5 million, and the national government added €60.6 million in 2025. De Torteltuin, part-financed by a citizen bond, is what that combination looks like when it lands.
Poland holds Europe’s largest cooperative stock by unit count, around 2.7 million homes, and Czechia about 480,000. Privatisation after 1990 left many of those spółdzielnie and bytová družstva administering flats their occupants now own outright. The collective management survived; the non-speculative tenure did not. Estonia went further and made apartment associations compulsory, which is not voluntary membership, though they became the vehicle for EU-funded energy renovation at scale.
Further east and south the statistics record close to nothing. New initiatives in Croatia, Serbia, Slovenia and Hungary face two construction projects at once: the homes, and the organisations able to build them. Czechia’s První vlaštovka is one of the few already standing. MOBA Housing SCE exists to supply what those groups cannot assemble alone.
Set the cooperative slice against every other tenure and the scale problem answers itself. In most of these countries it is a rounding error beside owner-occupation.
Underneath the national labels, five arrangements keep recurring. Each answers the same question differently: what stops the building being sold?
- Rental or right-of-use cooperative. The cooperative keeps the asset and members hold occupancy rights under its rules. Private gains are restricted and charges follow costs, though entry contributions vary widely. Switzerland, Austria, Germany, the Netherlands. See Zollhaus in Zurich.
- Ownership or shared-equity cooperative. The member holds a transferable share tied to one dwelling. Transfer values may be capped or left to the market, and tradability is precisely what wears the protection away. Sweden, Norway, Finland, Denmark.
- Grant-of-use (cessió d’ús). Collective ownership plus use rights that cannot be sold, almost always on a public-land lease. Catalonia, and increasingly copied. See Cirerers and La Balma.
- Community land trust hybrid. Land held in trust under a building owned or managed cooperatively, with resale restrictions on both layers. Belgium, France, the UK. See CALICO in Brussels.
- Solidarity syndicate. Each house is a company whose shareholders are the resident association and a syndicate holding nothing but a veto on sale. Strictly speaking not a cooperative, and in practice the tightest lock in the whole typology. Germany and Austria. See Bikes and Rails in Vienna.
Legal form on its own predicts almost nothing. Land terms, financing, the rules on private gains and the quality of governance decide what any of these delivers. Which leaves the obvious question: once people are living there, does any of it show up in their lives?
Does it actually work?
Cooperative housing is asked to do three jobs at once: hold a home affordable for decades, take the carbon out of it, and give the people inside somewhere they belong. The evidence for each is of a different quality, and the differences matter.
The money
Zurich’s cooperative rents run roughly 40% below the market rate in the same city. Berlin’s cooperative flats let at €6.27 per square metre against €15.78 for a new market contract. Read that pair carefully: it sets sitting tenancies against brand-new market lettings, so it measures the age of the stock as much as the tenure.
What the form guarantees is a direction of travel: a rental cooperative cannot sell the capital gain to anyone, so the gain stays in the charge. It guarantees nothing about the level of that charge, and a young cooperative on expensive land costs more than an old one that cleared its mortgage decades ago. The benefit leaks outward too. Austria’s limited-profit stock is associated with private rents around 5% lower across the wider market, a subsidy to people who never joined anything.
The carbon
Collective ownership stretches the decision horizon past the next sale, which is the horizon a deep retrofit needs. Members expecting to govern a building for thirty years price a renovation over its lifetime, and the best-known projects pair that with timber structures and low-tech servicing.
The sharper lever is one only a democratic landlord can pull: occupancy rules the members vote on themselves. In Switzerland, where minimum-occupancy rules are standard in the non-profit sector, private living space per person runs well below the national average in the dwelling sizes the rules cover. Floor area per head drives residential energy demand harder than almost any other variable, though the measured saving is in private area and shared rooms claw part of it back.
Rules alone are not enough. Polish and Czech cooperative retrofits move slowly and with little resident involvement. Ownership sets the horizon; capital decides whether anything happens inside it.
The people
A large household survey in Vienna found cooperatives generating linking social capital: access upward to housing managers and municipal decision-makers that most tenants never get. Those were big, professionally managed organisations, so the finding may belong to institutional scale rather than self-management.
At the individual level, a scoping review reports recurring evidence of social inclusion, less isolation and better mental health among older and lower-income residents. Residents of Catalan grant-of-use cooperatives rated their own health and social support higher after moving in, measured before and after without a control group. The one study using a comparison group found no significant difference in physical health.
Someone is missing from all of these studies: the household that could not get in. An entry share, spare evenings and the nerve to sit through two years of planning meetings select for people who already have some of each, and projects skew towards higher incomes and higher education. Without something that redistributes access to land and capital, it stays an alternative for what one review calls the ‘happy few’. So the interesting question is not whether cooperative housing works. It is why there is so little of it.
So why isn’t there more of it?
In Berlin, 92% of residents now know what a housing cooperative is, up from 61% when the survey series began in 2000, and 82% of those who know it could imagine living in one. What that appetite meets is a closed door.
Berlin’s cooperatives hold around 192,000 homes for roughly 317,000 members, and many have stopped admitting members altogether, having nothing to offer a new one in any year they can see. Amsterdam’s oldest cooperative, De Samenwerking, keeps more than 4,100 members on the books for 900 homes, and has shut its roll too.
The construction figures explain the queue. Berlin’s cooperatives completed 178 homes in 2025, their worst year in fifteen and more than 60% down on the year before. Austria’s limited-profit sector, the most institutionalised in Europe, completed 14,000 homes in 2024, some 16% below its ten-year average, with the leading indicators pointing lower still.
Targets have not closed the gap. Zurich’s voters wrote a one-third non-profit share of the rental stock by 2050 into the city constitution in 2011; the share then slipped from 29.3% to 28.9% between 2019 and 2023, a relative measure rather than proof the stock shrank. Amsterdam has committed to 40,000 cooperative homes by 2045, more than twenty-five times the entire current Dutch stock. Barcelona allocated 24 municipal plots carrying 849 homes under a 2020 agreement, and three have come forward in the past three years.
The ranking below is a photograph of where the stock ended up, not where it is growing.
Strong demand with closed admission rolls points at supply, not appetite. Five constraints keep turning up, in the research and in the accounts of people trying to build.
- Capital. New cooperatives need patient money without offering an unrestricted return, and lenders find capped returns, thin collateral and resident-led governance hard to underwrite. Established providers have the opposite problem: affordable rents do not throw off enough surplus to build at today’s prices. A large cooperative stock on a city map is not one large account; it is hundreds of separate balance sheets. Austria’s six housing-construction banks have issued roughly €23 billion in tax-privileged bonds since 1993, part-financing about every second home the sector built over three decades. Most countries have no equivalent, and CSEE initiatives run on project-specific grants.
- Land and buildings. In the cities where cooperatives are wanted most they bid against buyers who can pay more and close faster. Public-land leases, concept tenders, land foundations and community land trusts each cut the acquisition cost or lock land away from resale, and each depends on something fragile: municipal programmes on political continuity, independent trusts and foundations on assembling assets of their own. Switzerland’s umbrella body is building the Soliterra land foundation as a sector-wide answer.
- Delivery capacity. Money and a site are not a building. Germany’s Wohnungsgenossenschaften average well over a thousand homes each and employ people who have done this before; a new resident group has volunteers and no reserve to absorb a six-month delay. Federations can lend expertise or share risk, as Sweden’s regional associations do with development-loan guarantees, but only on the terms they choose.
- Governance quality. As a cooperative grows, professional staff make delivery better and scrutiny harder. Members struggle to challenge a proposal they lack the technical grounding to read. The research describes a risk of managerial dominance, not an inevitability — Vienna’s large limited-profit organisations show professionalisation can strengthen the link to institutions instead. The live question is which decisions stay with members.
- The enabling framework. Law shapes all four of the above. Austria has a dedicated limited-profit statute; much of Central and South-Eastern Europe has nothing comparable, so every project is negotiated from scratch. The European Affordable Housing Plan names cooperatives explicitly, though housing policy stays a national and local competence.
None of the five is fatal by itself. What makes them stick is that almost nobody is positioned to work on more than one at a time. A resident group in Ljubljana cannot borrow the Austrian bond market or the Zurich land office, however well those work at home.
Buildings you can go and stand outside
The argument stops being theoretical the moment you can stand outside one of these. Most of them settle a different objection.
Kalkbreite wraps housing around a working tram depot in Zurich, with shared kitchens, guest rooms and a public ground floor, on land the city leases rather than sells. Zollhaus, built by the same cooperative beside the railway, went further: flats handed over as raw halls for members to finish themselves, which is how its cheapest units got cheap. Together they answer the objection that non-market housing has to be dull.
Barcelona’s three make the Catalan case. La Borda was the first to prove a cooperative could win a public-land lease and build in timber on it. Cirerers and La Balma followed onto city-tendered sites and added shared space and social programming to the ownership rule. All three run on use rights that can never be sold, which is the point Spain’s tiny stock is making to the rest of Europe.
Möckernkiez is the largest recent resident-led development in Berlin, on a central site most developers would have filled with flats for sale. Brf Viva in Gothenburg put 132 apartments together with shared facilities, solar electricity and car- and bicycle-sharing instead of private parking, and remains ownership-aligned tenure, which is the honest caveat. De Torteltuin in Amsterdam raised part of its money from a citizen bond when the banks would not move.
CALICO in Brussels sits on land held by a community land trust with the building run cooperatively, and reserves homes for people at the very beginning and the very end of life. Bikes and Rails in Vienna is not legally a cooperative at all: it is a company whose second shareholder exists for one purpose, to refuse a sale. Die HausWirtschaft, also in Vienna, folds workspaces into the same membership as the flats.
None of these is a pilot waiting for permission. They are occupied, financed and audited. What they have never had is a way to lend each other money, staff or a legal template across a border.
The tier nobody has built yet
Cooperatives already share capacity. National federations handle development, financing and training for local members, so pooling beyond the single project is old practice. It simply stops at the border.
Two attempts at crossing it point in opposite directions. MOBA Housing SCE is a bottom-up federation of initiatives in Croatia, Czechia, Hungary, Serbia and Slovenia, pooling knowledge and building a shared revolving credit pool so each member develops and owns housing in its own city. LiM, founded in Berlin in 2018, did the reverse: a pan-European developer owning across several countries and leasing each project to a local operator. Its Berlin pilot was delivered, 40 timber flats on Ewaldstraße. The announced follow-ups in Latvia and Finland were not, and on liquidation in 2025 the Berlin building passed to its local partner.
Cultivate a network of cooperative housing entities across Europe.The sector has asked for the layer. In Housing Europe’s survey, Estonia’s EKYL asked the Union to “encourage collaboration around the EU and alliances between cooperatives”. That is a request for coordination, not a mandate for any particular legal vehicle, and the European Cooperative Society statute has existed for two decades without solving the capitalisation problem.
Look at the gap head-on and the missing layer becomes legible.
In Ostrom’s terms, a European level would be a nested tier: something supplying what a local group cannot assemble alone, without moving everyday authority away from the people living in the building. Patient capital. Buildings sourced across borders. Legal work done once and reused. Doing that without repeating LiM is a design problem, and the next deep dive takes it apart — who owns, who controls, who builds, who funds, and what stops any of them selling.
References
From our library31
- Collaborative Housing in Europe: Conceptualizing the Field — Knowledge
- Statement on the co-operative identity, values and principles — Knowledge
- Governing the commons: The evolution of institutions for collective action — Knowledge
- Housing Needs and Cooperative Housing Models: A Scoping Review — Knowledge
- Kalkbreite — Project
- Zollhaus — Project
- Die Hauswirtschaft — Project
- Möckernkiez — Project
- Prinz Eugen Park — Project
- The changing role of cooperatives in the Swedish housing regime — Knowledge
- Sostre Civic — Organisation
- La Borda — Project
- De Torteltuin — Project
- Housing Policies in the Service of Social and Spatial (In)Equality — Knowledge
- První vlaštovka, sociální družstvo — Project
- MOBA Housing SCE — Organisation
- Social-Ecological Cooperative Housing — Knowledge
- How to reduce? Legitimacy of housing sufficiency policies in the case of occupancy requirements in Switzerland — Knowledge
- Between efficiency and democracy: Explaining support and resistance towards energy transition and prosumer solutions in Polish and Czech housing cooperatives — Knowledge
- Cooperative housing and social cohesion: The role of linking social capital — Knowledge
- Cooperative housing: A catalyst for health and wellbeing? A scoping review of English and Spanish literature (2004–2024) — Knowledge
- Cooperative housing under a grant-of-use in Catalonia and health: pre-post analysis — Knowledge
- The effects of cohousing model on people’s health and wellbeing: a scoping review — Knowledge
- Public-cooperative policy mechanisms for housing commons — Knowledge
- Cirerers — Project
- La Balma — Project
- Brf Viva — Project
- Calico — Project
- Bikes and Rails — Project
- MOBA: Rethinking needs and financing for affordable rent and cooperative housing in Central and South-Eastern Europe — Knowledge
- Synthesis report on the application of Council Regulation (EC) No 1435/2003 of 22 July 2003 — Statute for a European Cooperative Society (SCE) — Knowledge
Further sources24
- European Housing Coop countries dataset — European Housing Coop countries dataset
- Collaborative housing in Europe: Conceptualizing the field — Housing, Theory and Society
- Beyond collective property: A typology of collaborative housing in Europe — International Journal of Housing Policy
- Housing cooperatives in Europe: Resilience and adaptation to changing needs — Housing Europe
- Housing co-operatives in Germany: 160 years of evolution and resilience — Journal of Co-operative Studies
- Housing cooperatives, housing systems and the state — Housing Studies
- Bengtsson, Housing Studies — Bengtsson, Housing Studies · 1945–1989
- Sanchez-Bajo, Cidades — Sanchez-Bajo, Cidades · 1980s–1990s
- GdW, Wohnungswirtschaftliche Daten und Trends — GdW, Wohnungswirtschaftliche Daten und Trends
- Statistics Sweden — Statistics Sweden
- Verordening Stimuleringslening wooncoöperaties Amsterdam — Verordening Stimuleringslening wooncoöperaties Amsterdam
- Rijksoverheid, Fonds Coöperatief Wonen — Rijksoverheid, Fonds Coöperatief Wonen
- European Housing Coop cities dataset — European Housing Coop cities dataset
- Klien et al., WIFO — Klien et al., WIFO
- forsa survey for the Berlin cooperatives — forsa survey for the Berlin cooperatives
- BBU Verband Berlin-Brandenburgischer Wohnungsunternehmen — BBU Verband Berlin-Brandenburgischer Wohnungsunternehmen
- Gemeente Amsterdam, Actieplan wooncoöperaties — Gemeente Amsterdam, Actieplan wooncoöperaties
- GBV Baubilanz 2024 — GBV Baubilanz 2024
- Stadt Zürich, Umsetzung wohnpolitischer Grundsatzartikel — Stadt Zürich, Umsetzung wohnpolitischer Grundsatzartikel
- Habicoop, Balaç i futur de l’habitatge cooperatiu — Habicoop, Balaç i futur de l’habitatge cooperatiu
- Riksbyggen — Riksbyggen
- LiM – Living in Metropolises SCE — LiM – Living in Metropolises SCE
- A coordinated EU approach to housing — European Parliamentary Research Service
- the next deep dive takes it apart