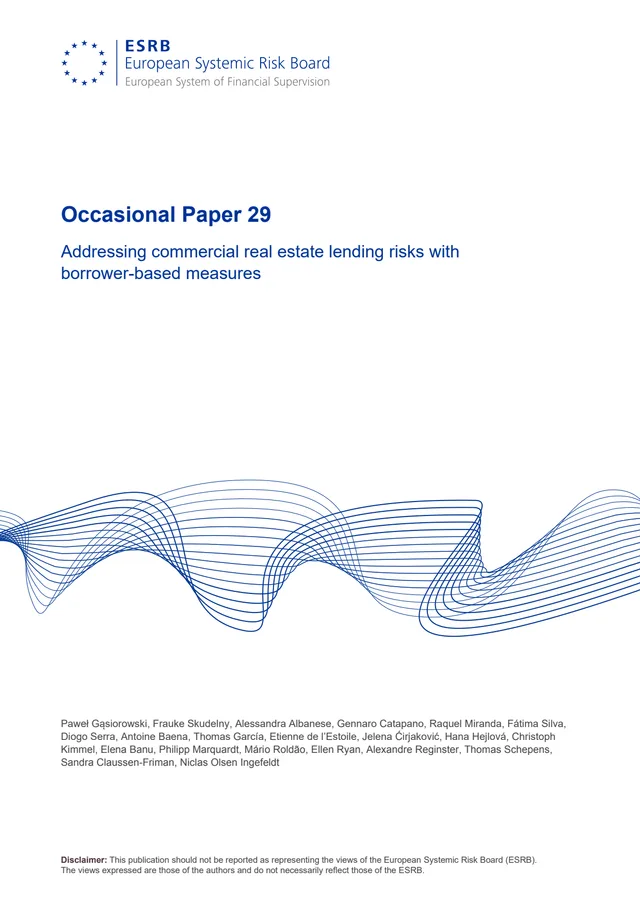
Overview of the Report
The European Systemic Risk Board (ESRB) published this occasional paper to analyse vulnerabilities in commercial real‑estate (CRE) lending across the European Union. The authors represent a broad consortium of academics and policy experts from institutions in Poland, Germany, Italy, Spain, the United Kingdom and other member states, bringing together expertise in finance, macro‑economics and sustainable development. Their joint effort reflects the ESRB’s mandate to monitor systemic risk and to propose macro‑prudential measures that safeguard financial stability while supporting the transition to greener housing.
Focus on Borrower‑Based Measures
The paper concentrates on borrower‑centred tools that can mitigate CRE‑related risk. It examines loan‑to‑value (LTV) caps, debt‑service‑to‑income (DSTI) limits, and the integration of sustainability criteria into credit underwriting. The authors quantify how tighter LTV thresholds—reducing exposure from the current average of 80 % to 70 %—could lower default probabilities by up to 15 % in stressed scenarios. They also highlight that applying DSTI limits tied to energy‑efficiency scores can encourage developers to adopt low‑carbon building standards.
Key Data on European CRE Exposure
According to the ESRB’s internal database, the total outstanding CRE loan portfolio in the Eurozone amounted to roughly €1.2 trillion in 2025, representing 14 % of total banking assets. Of this, about 35 % is linked to residential projects, while the remainder covers office, retail and logistics assets. The authors note that approximately 40 % of residential loans lack any explicit sustainability clause, underscoring a significant gap for policy intervention.
Sustainable Housing Implications
The study links borrower‑based measures to the EU’s Green Deal objectives. By mandating that a minimum share of new residential loans finance buildings meeting the Nearly Zero‑Energy Building (NZEB) standard, the ESRB estimates a potential reduction of 0.8 MtCO₂e in annual emissions from the housing sector. Moreover, the authors argue that incorporating climate‑risk stress tests into banks’ capital frameworks can improve resilience against climate‑related market shocks.
Recommended Policy Instruments
The authors propose a three‑tiered framework: (1) immediate implementation of LTV caps for new residential financing; (2) phased introduction of DSTI limits linked to verified energy‑efficiency certifications; and (3) creation of a harmonised European CRE‑risk register that tracks borrowers’ sustainability performance. They suggest that national supervisory authorities coordinate with the European Banking Authority to ensure consistent application across jurisdictions.
Expected Financial Impact
Simulation results indicate that the combined measures could shave €4.5 billion off banks’ risk‑weighted assets over a five‑year horizon, freeing capital for green lending. The paper also forecasts a modest increase in mortgage rates—around 0.15 percentage points—offset by long‑term savings from reduced energy consumption for borrowers.
Implementation Challenges
The authors acknowledge data‑availability constraints, noting that many lenders still lack granular information on the energy performance of existing properties. They call for enhanced reporting standards and for the development of interoperable databases to facilitate the verification of sustainability criteria.
Outlook for the EU Housing Market
The ESRB concludes that borrower‑based macro‑prudential tools, when aligned with the EU’s climate agenda, can simultaneously curb systemic risk and accelerate the transition to sustainable housing. The paper urges policymakers to act promptly, leveraging the identified measures to build a more resilient and greener European property market.