Does it add up?
Your city
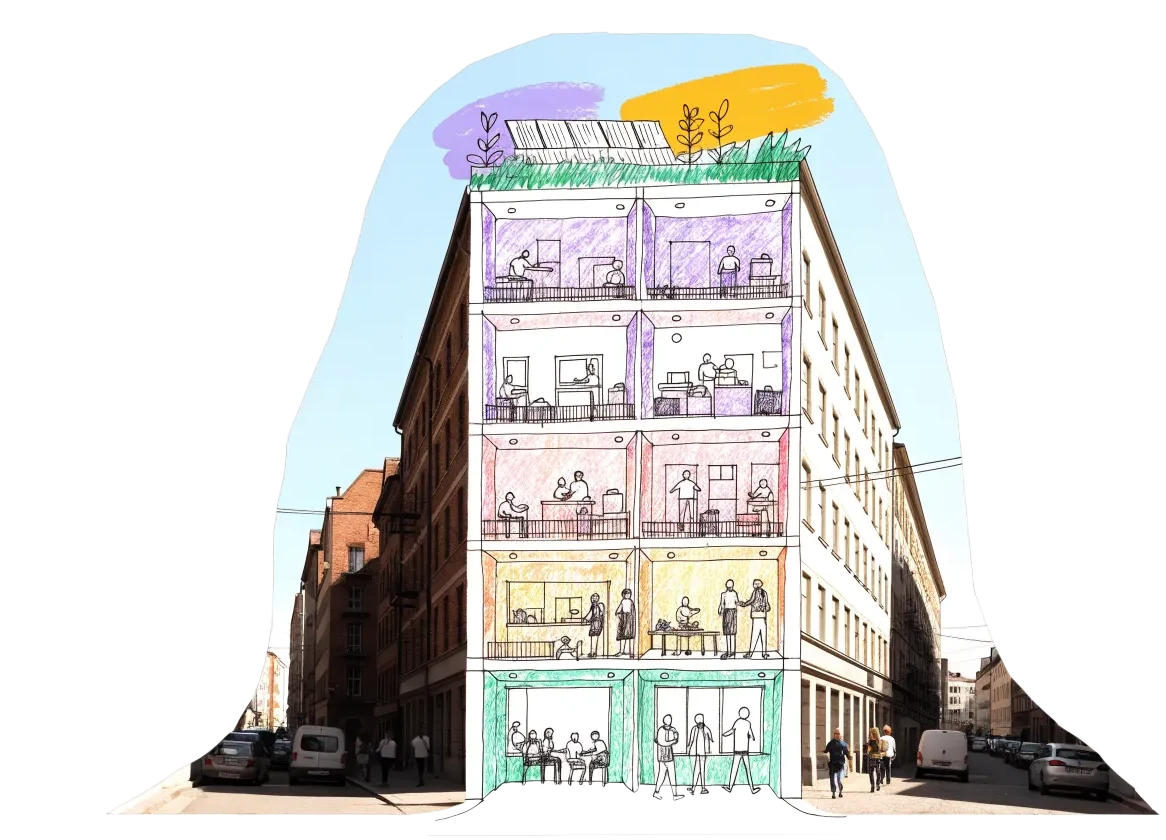
The short answer
In Berlin, a one-person flat costs €700 a month in year one, heating and utilities included — €27 more than the market’s €672 at first. By year 20 it is €805 against €1,128.
Every number here rests on assumptions we are still testing — 284 of them, each with a card. See them all, or try one:
The twelve assumptions that move the answer mostSlide any of them and the building’s numbers move with you
View as · 8 views, swipe →
The whole model, part by part. Pick who you are to see your answer first in each part.
The building
One converted building: what a home costs, where the fee goes, how renting, buying and joining compare over thirty years, what is inside and who pays for it.
What would I pay?
Take a one-person flat of 35 m² in a converted office in Berlin. In its first year you would pay €700 a month, heating and utilities included. That fee is a cost rent: it is set by what the building costs to finance and run, not by what the market will bear. The same flat on the open market asks about €672 with the same heating and utilities. So in year one you pay €27 a month more than the market, and you get about 4 m² of shared rooms on top: a big kitchen, a workspace, a roof terrace. For a nurse here, who takes home about €3,374 a month, that is 21% of pay; for a teacher (€3,647), 19%.
The difference is what happens next. The market charges what people will pay; the model assumes it keeps rising about 3% a year. The fee rises by 1.5% a year for the first 9 years. From year 10 it is held at the building’s costs plus a solidarity part of at most 10% of what the homes cost (heating and utilities aside), so it rises with the costs, about 0.3% a year, and never falls below them. By year 20 you would pay €805 where the market asks €1,128.
In the building’s year 36 its loan is paid off. It cost your home about €318 a month. Residents get 80% of it back: about €255 comes off your fee, so the fee you see drops by about €247 a month (27%), a little less than that because the year’s other costs rise. The other €64 keeps being charged and goes to the fund for the next building.
Over your first 20 years you would save about €20,000 against renting the same flat, counted in today’s money (about €276,000 over the model’s 60 years).
To move in you buy a stake of €30,676, refunded with inflation added when you leave: about €45,582 after 20 years — it keeps its value. The next member pays it: the stake a newcomer pays in rises the same way, to about €45,582 after 20 years, so the building pays nothing. It is about 90% of a year’s median income for a household like yours (the national median, not the city’s). You also join EHC: a €400 member share, refunded at face value, and €150 a year in dues. If the stake is more than you have saved: two ways to spread it — neighbours helping with a newcomer’s stake, and the fund lowering later residents’ stakes — are in the model but switched off in our version while we test them.
When? Work on a first building here starts in year 5 of the plan, and it would open about year 10 of the plan — finding, securing and converting a building takes a few years. These are the prices it would have. Homes are offered by member-years alone — the longer you have been a member, the earlier you are offered one; how long the wait would be is not in the model yet.
- Your fee
- What the building costs
- The market, same flat
- Solidarity contribution
- What you save
- Your fee
- €805
- What the building costs
- €748
- Solidarity contribution
- €57
- The market, same flat
- €1,128
- You save
- €322
Year 36, loan paid off: it no longer costs your home €318 a month. €255 of that comes off your fee (before that year's rise) and €64 keeps being charged and goes to the network, so the fee you see falls by €247 a month.
If you lived here for …
- What the building costs €86,300
- Towards the network (solidarity contribution and, once a loan is paid off, its freed repayment) €3,400
- Market rent €91,400
About the same as renting the same flat on the market for 10 years.
Your stake in €30,676 back €37,393 when you leave (worth €30,676 in today’s money after 10 years).
Where does my fee go?
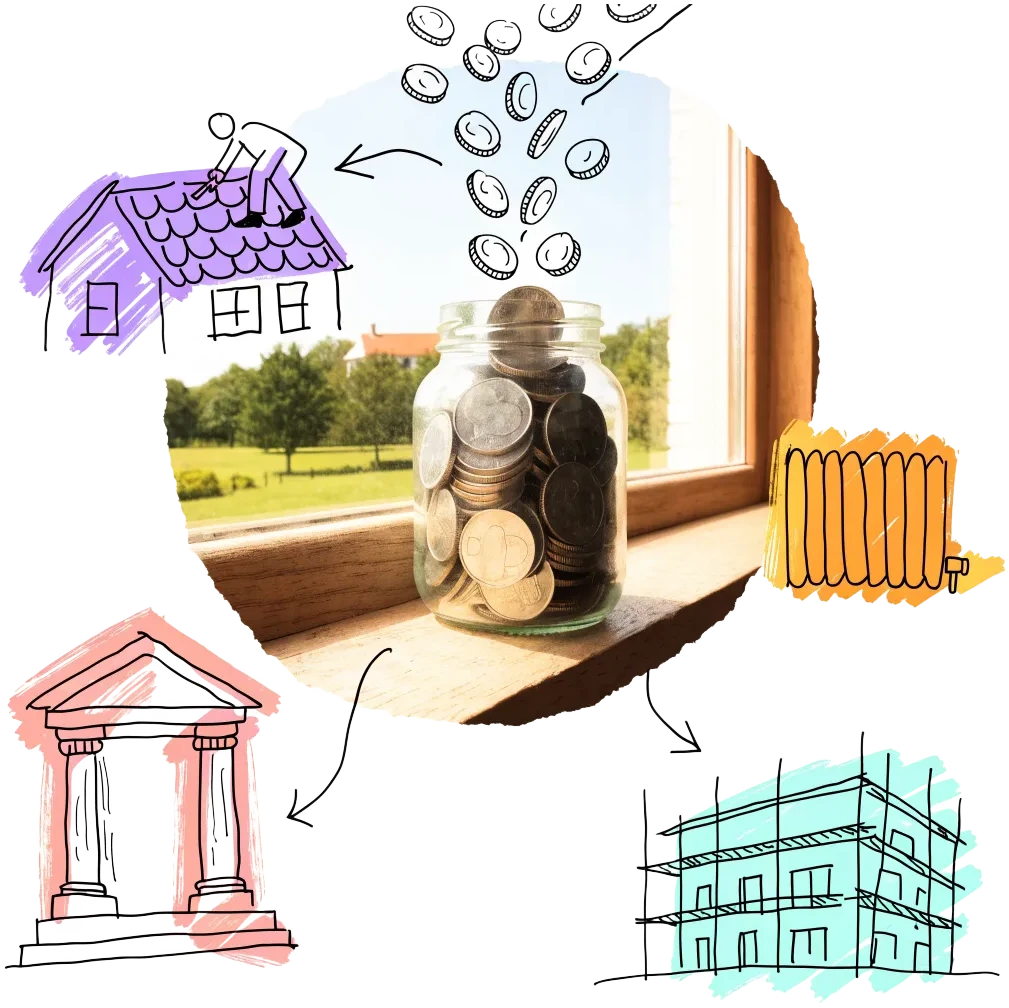
Every euro of the fee goes to this building — its loan, its running costs, the capped return on the money in it — and, from year two, a solidarity part, named on the fee, that buys the investors out and then funds the next building. None of it is profit: there is no landlord taking a margin on top, the line for profit is €0, and the building’s rules keep it there.
The biggest part, €260 of your €700, is the bank loan. The part for the long-term investors and EHC (€66) is a capped return of 3.5% a year on the money they put in — it can never be raised to squeeze more out of the building.
The fee rises 1.5% a year for the first 9 years, while the building’s own costs grow more slowly — the mortgage payment does not grow at all. The difference is named on the fee, not hidden in it: a solidarity contribution, about €57 a month by year 20. It is not profit. It first buys the investors out, for the building’s co-op as a whole (they are all repaid by the building’s year 17), and then goes to the fund that pays for the next building — a revolving fund, which puts each building’s money back to work in the next. And it is capped: never more than 10% of what the homes cost (heating and utilities aside). From year 10 the cap holds: the fee stops rising by 1.5% a year and is held at the building’s costs plus that part, so it rises with the costs, about 0.3% a year. The residents carry a small, visible part of the network’s growth: by the end of the plan, of the Fund’s money in the buildings about 5% came from residents’ solidarity parts and 94% from the people who use the network — the furnished flats and ground floors (70%) and the members, through EHC (24%).
Is that fair if you leave? Half of it goes into a loyalty account in your name — what co-ops call a patronage credit: a refund of what you paid for using the co-op, never a return on money. It keeps its value against inflation, becomes yours in equal steps over 10 years of membership, and is paid out over 3 years when you leave — about €1,517 after 10 years, €4,109 after 20 years and €6,315 after 30 years in today’s money. The rest stays with the network, and so does the building: it goes on to whoever lives in it after you, and your stake comes back with inflation added. Even with it, by year 20 you pay €322 a month less than the market; without it the fee would be €748. It is the price of a home that can never be sold on for a profit.
If the building’s costs ever rise faster than the fee would, the fee follows them: it never falls below what the building costs, and then there is no solidarity part that year. After the loan is paid off (the building’s year 36), the part of its old cost that is still charged shows on the fee as its own line, “the paid-off loan, towards the network”. Big repairs are paid first from the repairs saving in the fee — the building’s sinking fund. As a member you have one vote, like every other, in the co-op that owns the building.
Your fee €700 a monthMove the slider to see how each part changes over 30 years
- The bank loanInterest and repayment on the building’s mortgage.€260
- Upkeep and renewalRepairs, insurance, property tax and saving for the next new roof or boiler.€83
- Ground rentThe yearly rent for the land, because the building sits on a long lease instead of being bought.€89
- Running the buildingThe local partner who manages it day to day.€40
- The shared roomsBuilding and running the kitchen, workspace, kids’ room and roof everyone uses.€42
- Long-term investors and EHCA return capped in advance on the money they put in: €65 to the investors, €1 to EHC’s small permanent stake.€66
- Empty flats and unpaid rentA cushion so a few empty weeks never push the fee up.€14
- Solidarity contributionNothing yet: in year one the fee just covers the building’s costs. The fee rises 1.5% a year and the costs more slowly; the difference will first buy out the investors, then fund the next building.€0
- Heating and utilitiesWhat the flat uses — the same amount is added to the market rent it is compared with.€120
- Your two hours a monthResidents help run the place, and the fee is lower for it.−€15
- Profit for a landlordThere isn’t one. The investors get the capped return above, and nothing more.€0
- Your fee, year one€700
Rent, buy or join?
Owning gives people something renting never does: after thirty years, something to show for it — and a home no landlord can take away. So here is the same 35 m² flat in Berlin three ways, in today’s money, counting what each costs after what you would walk away with if you left: the deposit back if you rent, the flat sold if you buy, your stake, member share and loyalty account if you join. Heating and utilities are left out of all three: they cost about the same whichever way you live.
To buy it — about €215,000 — you need about €60,000 before you move in (a 20% deposit and 8% purchase costs), then €810 a month on a 3.8% mortgage over 30 years, and about 1.5% of its value a year for repairs, charges and tax. To join you need €31,076: the stake and the member share. To rent, a deposit of three months.
If you left after 30 years, renting would have cost you about €231,000, buying about €115,000 — you would have paid €394,000 and walk away with €280,000 — and joining about €174,000: €211,000 paid in, €37,000 back. Over 30 years buying costs the least here — about €59,000 less than joining — if flat prices rise 3% a year, and if you can find €60,000 to start. Joining asks €29,000 less up front, and carries no risk of the price falling or the mortgage rate rising.
Two assumptions decide most of this: how fast flat prices rise (3% a year here) and the mortgage rate — both are levers beside this chapter. A flat you own can also lose value, and a mortgage can cost more when its rate is fixed again. A co-op home can never be sold for a profit — this is a limited-equity co-op, where a member’s stake comes back at a set value rather than at the market price — but it cannot lose you money either: your stake comes back with inflation added.
What joining early adds is not only money. Every year as a member counts: member-years give you first offer on homes in new buildings, the right to move to another city in the network without starting at the back of the queue, and priority for the furnished flats. They never buy a vote — one member, one vote, however long you have been in.
Rent, buy or join: the same flat in Berlin
| Renting | Buying | Joining | |
|---|---|---|---|
| Needed before you move in | €1,657 | €60,303 | €31,076 |
| Paid in over 30 years | €231,516 | €394,468 | €211,183 |
| What you’d walk away with | €915 | €279,941 | €37,212 |
| What it really cost | €230,602 | €114,527 | €173,971 |
Buying: a flat at about €215,369, 20% deposit and 8% purchase costs, a 3.8% mortgage over 30 years (€810 a month), 1.5% of the value a year for repairs, charges and tax, prices rising 3% a year, 3% to sell. Joining: the stake, the member share, the fee and dues; back come the stake, the share and the vested loyalty account. Renting: the market’s rent and a deposit of three months.
What’s inside the building?
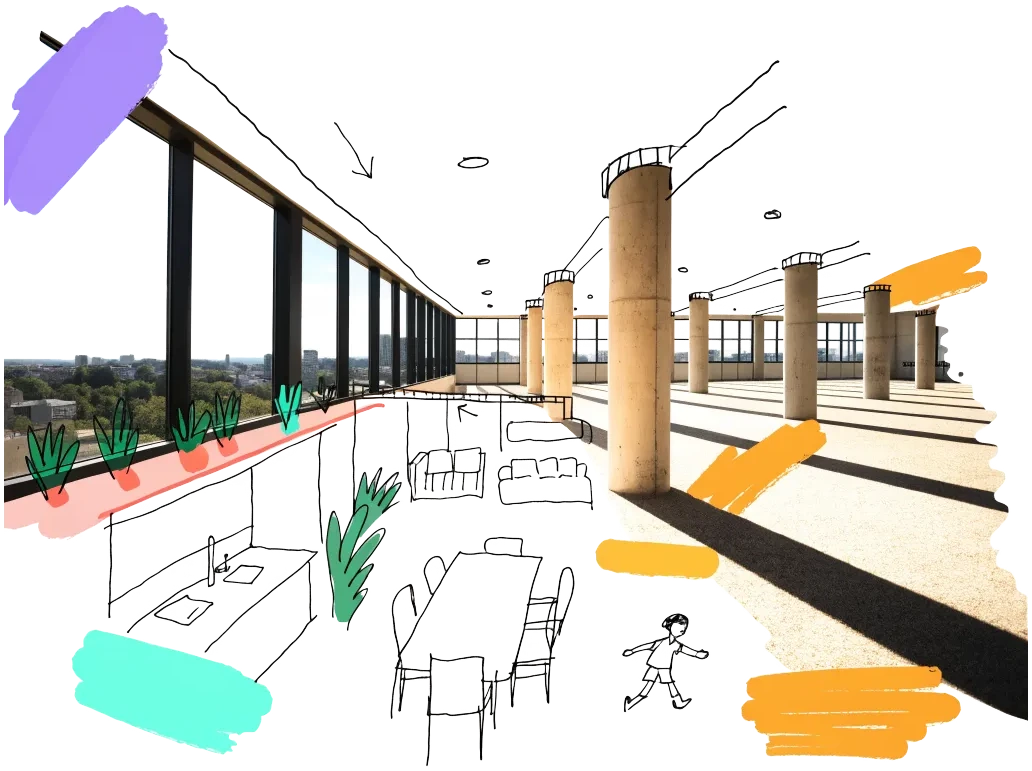
The building is an empty office of 7,500 m², converted instead of knocked down — adaptive reuse, in the trade’s words. That costs about 30% less than building new (€1,715 a m² against €2,450), and keeps about 2,250 tonnes of CO₂ out of the air: the embodied carbon that making the materials and building new would emit.
Inside: 53 homes for good, where 116 people live. Rooms everyone shares. 18 furnished flats for members moving between cities, let for three to twelve months (mid-term rentals): about 77 people stay in them in a year. And a ground floor for a café, a workspace and events.
The furnished flats and the ground floor are the building’s engine — a cross-subsidy, where the parts let nearer the market carry costs the homes do not. Each m² of furnished flat earns about 2.7 times what a m² of home does, each m² of ground floor 1.4 times. Their surplus — about €96,000 a year — pays the capped return on the money that built them and EHC’s fee for running the network. The homes pay their own way: their fee carries their share of the loan and the capped return on the money in the homes (about €79,000 a year across the building), but no margin and, in year one, nothing towards running the network. As the fee grows past the building’s costs, a named solidarity part appears (see “Where does my fee go?”): it buys the investors out and then funds the next building — the homes’ only contribution to the network.
What one m² returns in a year
after its own running costs and its share of the loan
A home earns only the small, capped return on the money in it (about €79,000 a year across the building, paid in the homes’ fees) — no margin, which is what keeps the fee low. The furnished flats and the ground floor earn more; their surplus, about €96,000 a year, goes to:
- The capped return on the money in these floors: €45,000 a year
- Running the network (EHC): €31,000 a year
- The building’s reserve: €20,000 a year
About 35 stays a year fit in this building’s flats; members want about 36.
Who pays for it?
Converting this building costs €17.5 million, everything included. About 59% is an ordinary bank loan over 35 years, its rate fixed for the first 10 — that share is the loan-to-cost ratio (LTC). The bank is repaid before anyone else, which makes it senior debt. The rest is equity, own money that is repaid only after the bank: the members’ stakes — the households’ and the businesses’ downstairs — and long-term investors, patient capital that accepts a low, capped return and a long wait. The land is on a 99-year ground lease — it stays with its owner, and the building pays a yearly ground rent for it — longer than the loan.
A bank lends only if the building’s net operating income (NOI) — what it earns after running costs, the ground rent, the repairs saving, a cushion for empty homes and unpaid rent, and the manager, not counting the residents’ volunteer hours — covers the loan payments with room to spare. That room is the debt service coverage ratio (DSCR): the NOI divided by the year’s loan payments, where 1.00 would only just pay them. And it never lends more than 80% of the cost. Here it does: a DSCR of 1.28, where a bank asks for 1.25. Put in more own money and the loan shrinks, so the fee falls. Put in too little and the bank says no.
The first year is the tightest: as the fee rises and the repayment does not, the DSCR grows to about 1.58 by year 10. But the margin at the start is thin — the picture below shows which assumptions would tip it.
What it costs · €17.5 million
- Converting the building€12.9 million 73%
- Design, permits and fees€1.5 million 9%
- A buffer for surprises (contingency)€1.3 million 7%
- Furnishing the flats€264,000 2%
- The developer’s and EHC’s fees€947,000 5%
- Interest while it is built€615,000 4%
Who puts the money in
- Bank loans€10.4 million 59%paid first: 3.8% over 35 years, fixed for 10
- Long-term investors€3.5 million 20%paid after the bank: a return capped at 3.5% a year, bought out at what they put in
- The residents’ stakes€3.1 million 17%paid back to each household when it leaves, with inflation added; no return
- Ground-floor businesses’ member shares€497,000 3%member shares, paid back when a business leaves; no return
A bank would lend: the rents cover the repayments 1.28 times — the DSCR — where it asks for 1.25.
Would a bank keep lending? The debt service cover (DSCR), year by year
- This version
- A bad decade
- Cover the year the rate resets
- Debt service cover (DSCR), year 1
- 1.28× · passes
- a bank asks 1.25×
- The loan
- €10.4 million
- 3.8% interest, over 35 years
- Rate fixed for
- 10 years
- then it resets, year 11
- Loan to cost (LTC)
- 59% · passes
- limit 80%, construction interest included
- Loan to value (LTV)
- 68%
- valued at €15.4 million: a year’s rents after running costs ÷ 4.5%
- Ground lease
- 99 years · passes
- outlasts the 35-year loan
Go deeper: every assumption behind the building 115Test them, change them, and see what moves
The organisation
Who owns the building, who earns what for the work, how investors get their money back, and how EHC pays its way.
Who owns it, and who decides?
At the start, long-term investors own about 50% of the building’s equity. Over time the building’s co-op buys most of them out together, out of the building’s own money; EHC buys the rest (about 19%) with its own money, up to its permanent stake. By the building’s year 17 they are all repaid. From then on that co-op owns 90% and EHC 10%.
The building sits in its own company — a special-purpose vehicle (SPV) — that holds this one building and its loan and nothing else, so no other building’s troubles can reach it. The co-op’s members are everyone who lives or trades in the building — a multi-stakeholder co-op, with more than one kind of member: its households, and the businesses downstairs, whose member shares are about 7% of the building’s equity. They have a long-term stake in the same place, and their rent helps buy the investors out too. What each member paid in comes back with inflation added when they leave; everything the co-op buys out of the building’s surplus is owned in common, so no member can cash in a share of the building.
Every member has a vote, but the households alone decide what only concerns the homes: the fee, who gets a flat, the house rules. The businesses’ rent is not put to a vote either — it follows a rule written into the lease — because it helps pay the investors back and funds the next building. The model assumes every business downstairs joins; one that would rather not could still rent the space, without shares and without a vote.
Nobody can sell it. A sale needs two keys turned at once — the co-op’s and EHC’s — and EHC’s key exists only to say no: a golden share, whose one right is to block a sale or a change of the building’s purpose. With the rule that no member can cash in a share of the building, it makes an asset lock: the building stays housing, held in common, whoever comes and goes. A bank that lends on the building keeps its normal rights over its security; how those rights sit alongside the veto is still to be settled with lenders.
How the building is held changes who earns what: an owner can sell it (about €6.6 million for the land, as the model values it), lease the land on a ground lease for a yearly ground rent (about €165,000 a year), or put it in for a share and a capped return — a contribution in kind (about €132,000 a year at first), which the building buys back over time.
Who owns the building
- The building’s co-op: its households
- The building’s co-op: the businesses downstairs
- Long-term investors
- EHC
- The local partner who builds and runs it€83,000 a year+ €628,000 once, for building it
- Long-term investors3.5% a year, cappedthen paid back and gone
- EHC, for the platform and the network€42,000 a year+ €319,000 once, for putting it together; the capped return on its permanent stake stays in the Fund
- Anyone, from the building getting more valuable€0it can never be sold
How do investors get their money back?
Outside investors put €3.5 million into this building through the Fund (with EHC’s own stake of €35,000, that is the €3.5 million of long-term money in the money chart). They are patient capital: they earn a capped return of 3.5% a year on what is still in — nominal, before inflation; about 1.5% real, after it, at 2% inflation — and their money is locked in for 5 years, a lock-up in which it cannot be taken out.
After that they are bought out at par — at exactly what they put in, no more. The building’s co-op buys most of them out together, out of the building’s own money; EHC buys the rest (about 19%) with its own money, up to its permanent stake. They are all repaid by the building’s year 17. In all they get back 1.40 times what they put in — their money multiple — an internal rate of return (IRR) of 3.2% a year: the one yearly rate that makes what they put in equal to everything they get back, whenever it is paid. About €1.4 million of it is return.
The buy-out is paid 20% from the solidarity part of the homes’ fee, 61% from the furnished flats’ and ground floor’s surplus and 19% by EHC, which buys up to its small permanent stake as the guardian of the mission. Once the investors are out, that money goes to the fund for the next building — about €48.2 million from this one over the horizon, in each year’s own money.
Each year the building’s money is paid in a fixed order — the payment waterfall, in which each level is paid in full before the next gets anything: the running costs, the manager, the bank, the investors’ capped return, then EHC’s fee. What is left goes, in this order, to the loyalty accounts of households who left, the investors’ buy-out (kept for it while they are still locked in) and the fund for the next building. If a year cannot pay everything, the capped return that goes unpaid is not lost, because the return is cumulative: it is owed to the investors and paid first from later years, before anyone is bought out, while EHC’s fee for that year is cut.
What an investor should also know: the Fund charges no fee in our version (its running costs are not set yet); EHC’s first-loss stake — its own money in each building, which takes any loss before the investors’ does — is small; and money invested in buildings outside the euro carries a currency risk the model does not include yet.
- The capped return
- Their money paid back
- Still invested in a bad decade
- Put in
- €3.5 million
- What it earns them
- 3.2% a yearbefore inflation; capped at 3.5%
- Money back
- 1.40 timeswhat they put in, in each year’s money
- Repaid by
- year 17in a bad decade: not within 60 years
- Locked in for
- 5 years
Who earns what for the work?
The people who do the work are paid for it, not for the building getting more valuable. One local partner — a housing co-op, a non-profit housing association or an impact developer — builds the building and then runs it. Building it earns €628,000 once — a development margin of 4% of the works, the design fees and the contingency (the buffer set aside for surprises), about €126,000 for each of the roughly 5 years from finding the building to opening it (before any overrun), paid when the building opens. Running it earns a management fee of €83,000 a year — about €1,188 a flat, of which about €238 is left after the cost of doing the job.
The works are bought on a target-cost contract, which shares both an overrun and a saving between the building and the developer — the pain share and the gain share. If they cost more than planned, beyond the contingency, the building and the developer split the difference 50/50 — and the developer never loses more than its margin. If they come in under the target cost, the developer earns 50% of the saving (at most its margin again) and the building keeps the rest. The buffer itself is the building’s reserve, not the developer’s to save: what is left of it stays with the building. Delays are in the model only as the bad decade’s extra year of works; the risk of a building failing to get planning is not in it yet.
The bank earns its interest — about €396,000 in the first year. EHC earns about €42,000 a year from this building (a platform fee from the furnished flats and ground floor, and a small booking fee on stays), and an origination fee of €319,000 once, for putting the project together. The capped return on EHC’s own permanent stake in the building is not part of that: it is paid to the Fund, where it stays.
The building’s year, in the order it is paid
The investors are still locked in, so what is left is kept for their buy-out.
- Everything the building takes in (the homes’ fees, the furnished flats, the ground floor)€1.2 million
- Running costs: upkeep, insurance, tax, ground rent, repairs saving−€387,000 33%
- The local partner who manages it−€83,000 7%
- The bank: interest and repayment−€543,000 46%
- The capped return on long-term money (investors, EHC)−€124,000 10%
- EHC’s platform fee−€31,000 3%
- Left over this year€20,000
- Where what was left went (it can include money kept in earlier years)Kept for the investors’ buy-out (still in the lock-up)€20,000
One building, from finding it to running it
- Preparation · about 2 years
Finding the building, the design and the permits. Who pays for this time is not in the model yet — nobody is paid for it here.
- Works · 3 years
The local partner converts it on a target cost and is paid its margin, €628,000, once, when the building opens.
- Running · from year 1, for good
The same partner runs it for €83,000 a year (one tick a year on the bar), of which €17,000 is left after its own costs.
Running it · per flat, a year
- The fee the local partner is paid€1,188
- Its own costs of doing it€950
- Left for it€238
Across the building’s 70 homes and furnished flats: €83,000 a year paid, €17,000 of it left after costs.
Building it · paid once
- Development margin
- €628,0004% of the building cost
- For each year of work
- €126,000over 5 years, about 2 of them preparation
- Target cost €12.9 million
- Contingency, the buffer for surprises €1.3 million
How does EHC pay its way?
EHC is the umbrella cooperative: it finds the buildings, puts each project together, runs the platform members book through and guards the mission. It is paid from four places: a platform fee from each building’s furnished flats and ground floor, a small booking fee on stays, one-off fees as buildings open, and members’ dues — €150 a year from a person today, and more from companies. The capped return on EHC’s own permanent stake in each building is not among them: it is paid to the Fund, where it stays.
In year 10 it takes in about €2.7 million and spends €3.2 million on its teams. By year 60 it takes in €74.8 million a year, the largest part from the platform fee on the buildings’ flats and ground floors, and spends €69.5 million — a surplus of about 7% of its income. Dues from people come to about €23 a year for each member by then, after the cut described below. These are in each year’s own money, so year-60 euros are worth far less than today’s.
EHC pays no dividends: a cooperative has no shareholders to pay. Any surplus goes into buildings first: by year 60 EHC has €420 million of its own money in the buildings, through the Fund — its permanent stakes, and its surplus wherever the next buildings need it before outside investors — and keeps €102 million in cash: its reserve, and what the buildings do not need yet. Its members’ shares carry it through its first years, but only just: its cash is lowest in year 5, at about €2.8 million. Later, once growth no longer needs it — from year 43 — the network hands its surplus back as lower prices, in proportion to who paid it in — a patronage refund, as co-ops call it: by year 60 members’ dues are 95% lower, the furnished flats and the ground floors cost about 38% less, and the households’ solidarity part is 94% smaller (see “How does one building become many?”).
- Income
- €74.8 million
- Running costs
- €69.5 million
- Surplus
- €5.3 million 7%
- Cash, year end
- €102 million
- Staff
- 93 FTE 88–108 as AI goes
- Finding and converting buildings 13
- Countries and new cities 20
- Members and campaigns 27
- The platform and technology 5
- Leadership, finance, law and governance 29
- Founding money raised at the start+€2 million
- Members’ shares paid in+€64.4 million
- Surplus or deficit, years 1–60 added up+€455 million
- Put into EHC’s own stakes in the buildings−€420 million
- In the bank at the end of year 60€102 million
EHC means to keep 15 months of running costs in cash — about €86.8 million in year 60, and it does.
EHC’s account never goes below zero on these numbers — at its lowest about €2.8 million, in year 5.
Members’ shares stay in the bank until EHC covers its costs and its reserve; until then outside investors hold EHC’s stakes in the first buildings, and EHC buys them as its surplus allows.
Go deeper: every assumption behind the organisation 85Test them, change them, and see what moves
Growth
How one building becomes a network, what member companies get from it, and what happens in a bad decade.
Where do we start, and why there?
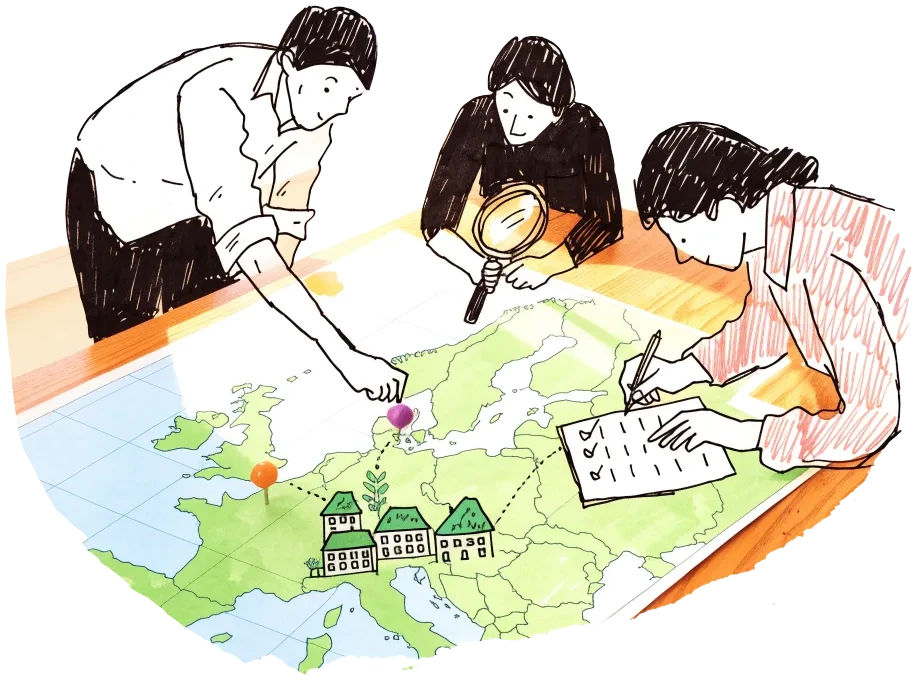
Before a single building comes the question of where. The network does not start where it happens to know people: it ranks the 183 European cities we have figures for on ten things that decide whether a building works there and helps the people in it — how far below the market the fee lands, how hard the squeeze on renters is and how many people rent; how little own money a building needs and how many offices stand empty; how many people come for months and how big the city is; and public support, the co-ops already there and the euro. In our version each counts the same; change what counts below and the order changes with it. On our weights the strongest are Munich, Berlin, Frankfurt am Main.
The first cities — Munich, Vienna, Paris — are the best-ranked in the countries the network starts in; after them it takes the others in order of their score, no more than 5 in any one country. It opens them slowly at first and faster as it grows — a young network has few local partners, no tested way yet of turning an empty office into homes and little money of its own; an older one has all three — so no new city opens in years 2–4 and Berlin starts only in year 5. In all it opens 5 new cities in the ten years after the start and 21 in the plan’s last ten. A good score is not enough, though: a city opens only if a bank would lend on its building with the own money the plan puts in. 56 of the ranked cities don’t pass that test yet — 46 because the rents would not cover the loan, 10 because too little would be left for the investors; the next city takes their place, and they wait for more own money or a grant.
Berlin is in the plan, 2nd on the score: work starts in year 5 of the plan, its first building would open about year 10, and it gets about 36 buildings over the plan. Of the 38 cities we model in most detail, the building adds up with the home at or below the market (within 3%) in 32 — not yet in Berlin, Hamburg, Helsinki, Mannheim and 2 more.
What empty offices could become · homes, by country
about 81,986 homes in the empty offices of the 62 cities we have figures for. By the end of the plan the network’s buildings hold about 26,527 homes and furnished flats — offices and other empty buildings together.
- Germany30,605
- Spain9,426
- France8,154
- Finland6,889
- Italy5,075
- Belgium4,599
- Netherlands3,469
- Denmark2,340
- Ireland2,046
- Lithuania1,776
The readiness score · the top 12 of 183 cities
- 1MunichGermany73opens year 1strongest on little own money needed, the EU and the euro, public support
- 2BerlinGermany70opens year 5strongest on the EU and the euro, how many people rent, size of the city
- 3Frankfurt am MainGermany69opens year 7strongest on the EU and the euro, little own money needed, how many people rent
- 4HamburgGermany68opens year 9
- 5ViennaAustria68opens year 1
- 6ParisFrance68opens year 1
- 7AmsterdamNetherlands67opens year 10
- 8DublinIreland67opens year 11
- 9BarcelonaSpain65opens year 12
- 10CopenhagenDenmark65opens year 14
- 11MilanItaly64opens year 15
- 12MadridSpain64opens year 16
- Where it helps most
- Buildings that add up
- People to fill them
- Ground to build on
What countsEach of the ten criteria counts the same in our version. Weigh them your way and the ranking and the plan follow.
The plan, in order · 77 cities
| # | City | Work starts | Buildings | Same flat, year 1 | Score |
|---|---|---|---|---|---|
| First, the best city in each of the 3 starting countries | |||||
| 1 | Munich | year 1 | 25 | 21% below | 73 |
| 2 | Vienna | year 1 | 19 | about the market | 68 |
| 3 | Paris | year 1 | 28 | 37% below | 68 |
| Then every other city, highest score firstNo new city opens in years 2–4, so Berlin starts in year 5. The network opens cities slowly at first and faster as it grows: 5 new cities in the ten years after the start and 21 in the plan’s last ten. | |||||
| 4 | Berlin | year 5 | 36 | 4% above | 70 |
| 5 | Frankfurt am Main | year 7 | 16 | 7% below | 69 |
| 6 | Hamburg | year 9 | 22 | 4% above | 68 |
| 7 | Amsterdam | year 10 | 10 | 42% below | 67 |
| 8 | Dublin | year 11 | 5 | 45% below | 67 |
| 9 | Barcelona | year 12 | 8 | 50% below | 65 |
| 10 | Copenhagen | year 14 | 9 | 19% below | 65 |
| 11 | Milan | year 15 | 9 | 38% below | 64 |
| 12 | Madrid | year 16 | 25 | 52% below | 64 |
Not viable yet · 56 cities
- Helsinkithe rents would not cover the loan — it would need about 45% own money (€629,000 more a building)
- Wrocławtoo little is left for the investors — it would need about 62% own money (€31,000 more a building)
- Krakówtoo little is left for the investors — it would need about 62% own money (€34,000 more a building)
- Odensethe rents would not cover the loan — it would need about 57% own money (€3.3 million more a building)
- Linzthe rents would not cover the loan — it would need about 72% own money (€4.5 million more a building)
- Turkuthe rents would not cover the loan — it would need about 51% own money (€1.6 million more a building)
- Uppsalathe rents would not cover the loan — it would need about 89% own money (€10 million more a building)
- Göteborgthe rents would not cover the loan — it would need about 69% own money (€5.8 million more a building)
A one-person flat in Berlin · € a month, warm
- Our fee
- The open market, same flat
- The city’s public rent cap (today’s)
- Homes kept affordable for good
- 53in this one building
- CO₂ kept out of the air
- 2,250 tby converting instead of building new
- Cheaper than building new
- 30%€5.5 million saved on one building
- Berlin in the plan
- about 36 buildingsabout 1,908 homes
How does one building become many?
When a building’s loan is paid off, in the building’s year 36, 80% of what the loan cost comes off the residents’ fee, and the other 20% keeps being charged and goes into the fund for the next building. Meanwhile the furnished flats keep members moving between cities, and the ground floors keep each building in its neighbourhood.
Run that across Europe, building by building: by year 10 of the plan the network is in 7 cities with 352 homes and furnished flats; by year 20, 17 cities and 2,463. The plan runs to year 60, when it reaches 77 cities in 26 countries, 26,527 homes and furnished flats, and 132,330 members. At its busiest it needs up to €262 million of outside investors’ money at once; by year 38 of the plan the last of it is paid back and the network pays for itself.
Each city takes only the buildings EHC can really find there: about 5% of the empty buildings that could become homes and pay their way — 10% of its empty office floor to start with, and the offices converted each year after that; and, from year 8, other empty buildings as well — schools, churches, barracks and public offices, department stores — adding about 40% more by year 20, more in the north-west, where churches are closing fastest and non-profit and public channels are strongest, and fewer in Central and Eastern Europe. A city opened is good for at least 2 buildings, and a local partner starts about 0.5 a year there.
Once it pays for itself, the network puts its own money to work in this order. First, more homes: by year 60 it has started about 29 more buildings than at the planned pace — at most 2 times the planned pace, because teams and partners limit how fast buildings can really start. Then, whatever it does not need — beyond 3 years of building kept in hand — it stops collecting, from year 43 of the plan, and hands back to whoever paid it in, in proportion. By year 60 members’ dues are 95% lower, the furnished flats and the ground floors cost about 38% less, and the households’ solidarity part is 94% smaller. It is a patronage refund — a refund of what they paid for using the network, never a dividend; EHC hands back only its own surplus, never below its costs.
2,463 homes
19,303 members
17 cities
- Open by year 20
- Later in the plan
- Not viable yet
- Berlin
- Cities
- 77
- Countries
- 26
- Buildings
- 377
- Outside money at the peak
- €262 million
Bank loans arranged, all years added up
EHC’s and members’ own money in buildings
Outside investors’ money in the buildings
- Bank loans arranged by year 60
- €6.9 billion
- Outside investors in the buildings, at the most
- €262 million
- All of them bought out by
- year 38
- Own money in buildings by year 60
- €420 million
What the Fund’s money in the buildings stands on, by year 60
- The residents’ solidarity part 5%
- The furnished flats and ground floors 70%
- EHC’s members (shares, dues and fees) 24%
What’s in it for companies?
We start with a founding pool of 50 member companies and 1,000 individual members. Companies join from anywhere — they work across city and national borders, so they need not sit in a city we build in; the flats and the work are in the network’s cities. After that, more join as the network opens cities and buildings: about 15 for each active city and 3 for each open building, and some leave each year. By year 20 there are about 305; by year 60, 1,876.
Membership costs more the bigger the company: from €500 a year for a company with under 10 staff to €50,000 for one with 10,000+ staff, plus a €6,500 member share that is refunded — placeholders we are testing, and the 250–9,999 band is too wide to be the final word. In return, member companies can book the furnished flats for staff who move for work from about year 6, when the first buildings open (none are kept aside for them on these settings: they book like any member), and bid to supply the building work and the upkeep, cleaning and furnishing the buildings buy — about €222 million of work a year by the end, in that year’s money. How the bidding would work is not designed yet.
Membership by company size · the fees are placeholders we are testing
Under 10 staff
€500 a year
- Share of members
- 30%
- By year 60
- about 563
- Dues that year, before relief
- €905,000
10–49 staff
€2,000 a year
- Share of members
- 30%
- By year 60
- about 563
- Dues that year, before relief
- €3.6 million
50–249 staff
€5,000 a year
- Share of members
- 22%
- By year 60
- about 413
- Dues that year, before relief
- €6.6 million
250–9,999 staff
€15,000 a year
- Share of members
- 15%
- By year 60
- about 281
- Dues that year, before relief
- €13.6 million
10,000+ staff
€50,000 a year
- Share of members
- 3%
- By year 60
- about 56
- Dues that year, before relief
- €9 million
- Member companies, year 10
- 123
- Year 20
- 305
- Year 60
- 1,876
- All companies’ dues, year 60, before relief
- €33.8 million
What if things go wrong?
Everything above is the realistic case — the base case. Below is the same building in Berlin in the realistic case, in a good decade and in a bad one — the downside scenario: a recession where the furnished flats stand emptier, the ground floor has to let at a discount, more people fall behind on rent, conversions take a year longer and run dearer, and market rents dip and then rise only slowly. It does not include interest rates rising when the loan’s fixed rate ends — the refinancing risk — test that with the rate-reset lever under “Who pays for it?”.
A bad decade is the honest test for a building that charges what it costs. The homes still pay their own way — the fee rises to cover the dearer building. What bends is the rest: the building as a whole covers its loan by less, the investors wait longer, and a new building needs much more own money before a bank will lend. Pick a card and the whole page follows it. Across the network, 19 of the 77 cities in our plan would still add up in a bad decade; the rest would wait for more own money — “Every city we model” under Go deeper lists which.
Go deeper: every assumption behind growth, and where to grow 55Test them, change them, and see what moves
Which seat is yours?
A home, a project, a company, or money that can wait: every one of these buildings needs all four at the table.
You would bring
Your demand, your sense of how you would actually want to live, and a couple of hours a month once there is a building to run.
You would get
A home you co-own, at a rent that follows what it costs rather than what the market will bear — long-term, or for a while, in whichever city you happen to be.
Check our working
Every number on this page rests on assumptions. Each one has a card: its value, where it comes from, how sure we are and whether we are testing it. If you think one is wrong, change it here and tell us.
What the model doesn’t answer yet
Questions each of you asked that the model cannot answer yet. Pick your seat; if you know how one should work, tell us.
32 open questions from 7 seats
Someone looking for a home
How long the wait for a home is
Homes are offered by member-years alone — the longer you have been a member, the earlier you are offered one — but the model does not count the queue yet.
The loyalty account’s legal form in each country
A credit on the member’s share balance, which co-op law allows — still to be checked.
When a leaving resident’s stake is paid
And what happens if many leave at once.
Moving your stake to a building in another city
A household that grows or shrinks
And a stake passed on at death.
A fee held below cost in a bad decade
Whether that ever happens when the market falls under the fee.
Who decides about the homes
How the households’ sole say over the homes is written into the co-op’s rules, next to the businesses’ vote.
Something missing from the list?
The terms we use41 terms a banker or housing professional would use, each in plain words
- Cost rent — a fee that covers the building’s costs
- Rent set by what the building costs to finance and run, not by what the market will bear.
- Revolving fund (our Surplus Pool) — the fund for the next building
- Where a building’s surplus goes once its investors are bought out, and later part of what its paid-off loan used to cost, to put into the next buildings.
- Patronage credit — your loyalty account
- A share of what a member paid in that the co-op keeps in their name and pays back when they leave — a refund of use, never a return on money. It becomes the member’s in equal steps over 10 years of membership and is paid out over 3 years once they leave.
- Sinking fund — the repairs saving
- Money put aside from the fee every year so that big repairs and renewals are paid for when they come.
- Limited-equity co-op — a home that can never be sold for a profit
- A co-op where a member’s stake comes back at a set value — here its face value, or with inflation added — never at the market price.
- Adaptive reuse — converted instead of knocked down
- Giving an existing building a new use, keeping its structure.
- Embodied carbon — the CO₂ building new would emit
- The emissions from making the materials and putting up a building, before anyone lives in it.
- Mid-term rentals — furnished flats for members on the move
- Furnished flats let for three to twelve months, between a hotel stay and a lease.
- Cross-subsidy — the building’s engine
- The parts let nearer the market — the furnished flats and the ground floor — earn a surplus that carries costs the homes do not.
- LTC (loan to cost) — the loan as a share of the cost
- The bank loan as a share of what the conversion costs, everything included.
- Senior debt — an ordinary bank loan
- A loan that is repaid before anyone else is paid — investors, EHC or members.
- Equity — own money
- Money put in for a share of the building rather than lent, and repaid only after the bank: the members’ stakes and the long-term investors’ money.
- Patient capital — long-term investors
- Equity that accepts a low, capped return and a long wait, in exchange for a social return.
- Contribution in kind — the owner puts the building in
- An owner puts the building in for a share and a capped return instead of selling it; the building buys that share back over time.
- Ground lease — the land on a lease
- The land stays with its owner for a fixed term; the building pays a yearly ground rent for it.
- NOI (net operating income) — what the building earns after its running costs
- The building’s income after running costs, ground rent, the repairs saving, a cushion for empty homes and unpaid rent, and the manager’s fee — before the loan.
- DSCR (debt service coverage ratio) — would a bank lend?
- The NOI divided by the year’s loan payments; 1.00 would only just pay them. The bank in our model asks for 1.25 or more. We leave out residents’ volunteer hours.
- LTV (loan to value) — the loan against what the building is worth
- The loan as a share of what the building is worth — here estimated from its income and a valuation yield.
- Viability gap — the gap a city, a funder or a partner would have to close
- The own money or grant a building still lacks before a bank would lend and its investors and EHC could be paid.
- SPV (special-purpose vehicle) — the building’s own company
- A company that holds one building and its loan and nothing else, so each building’s finances stay separate.
- Multi-stakeholder co-op — the building’s own co-op
- A co-op with more than one kind of member — here the households and the businesses downstairs — and rules on what each kind decides.
- Golden share — a veto that stops a sale
- A share whose only right is to block the sale of the building or a change of its purpose.
- Asset lock — nobody can sell it
- Rules that keep the building housing and held in common: it cannot be sold, and no member can cash in a share of it.
- Nominal / real — before / after inflation
- A return or a price as paid, and the same with inflation taken out.
- Lock-up — locked in
- The years in which investors cannot take their money out.
- At par — at exactly what they put in
- Repaid at face value — the amount put in, no gain on top.
- Money multiple — what they get back in all
- Everything an investor gets back, divided by what they put in.
- IRR (internal rate of return) — a return of … a year
- The one yearly rate that makes what an investor puts in equal to everything paid back, whenever it is paid.
- Payment waterfall — the order the building pays in
- The fixed order a year’s money is paid in, each level in full before the next gets anything.
- Cumulative return — an unpaid return is owed, not lost
- A return that a bad year cannot pay is carried forward and paid first from later years.
- First-loss capital — EHC’s money takes the first loss
- Money that takes any loss before other investors’ money does.
- Development margin — what building it earns
- What the developer earns for building it, as a share of the works, design fees and contingency.
- Contingency — the buffer for surprises
- Money set aside in the budget for the works for what nobody planned.
- Management fee — what running it earns
- What the operator is paid each year for running the building.
- Target-cost contract (pain/gain share) — the works bought on a target cost
- The works have a target price; an overrun and a saving are both shared between the building and the developer.
- Origination fee — for putting the project together
- A one-off fee for finding a building and putting its project and financing together.
- Patronage refund — handing the surplus back as lower prices
- A co-op’s surplus paid back to members in proportion to what they paid for using it — never a dividend on money.
- Base case / downside scenario — the realistic case / a bad decade
- The central assumptions, and the same model under a recession: emptier flats, more arrears, dearer and slower works.
- Refinancing risk — rates rising when the fixed rate ends
- The risk that the loan costs more once its fixed rate runs out.
- Engine room — the furnished flats and the ground floor
- Our name for the parts of the building whose surplus pays the capped return on the money in them and EHC’s platform fee.
- Member-years — your years as a member
- Our name for time in the network. It earns priority for homes, moves and furnished flats; it never earns a vote.
Where we are
- DoneUntil summer 2026
Finding a model that works
Build the economics in the open, on real data from over 100 European cities, so anyone can check whether affordable non-speculative homes actually add up.
- We are hereAutumn 2026 – summer 2027
Testing the appetite
Find out who is ready to move: 1,000 individuals and 100 companies willing to found a pan-European cooperative, and the first cities and buildings with the right conditions.
- NextSummer 2027 and beyond
Building the EHC
If the appetite is there and the model holds: found the organisation, raise the capital, and start the first pilot conversions.